Friday, 26 April 2019

New life at last for $20-million lost land in downtown Hamilton

 New life at last for $20-million lost land in downtown Hamilton

Nearly two acres, bounded by Main, Hess, Caroline and George, was nothing but a parking lot for decades. It’s been sold for just over $20 million.


Opinion Apr 09, 2019 by Paul Wilson Special to The Hamilton Spectator


At the corner of Main and Walnut, change came fast. Work is now underway on this 25-storey residential tower. - Vrancor Group
This building fell fast at Main and Walnut last year, and was once the handsomely-landscaped national headquarters of an accountants’ society. - Google Street View 
Several decades ago, a developer knocked down apartments along this stretch of Main for a condo that never happened. All these years later, the land has changed hands for $20 million, with big development coming. - Paul Wilson 
This downtown block, bounded by Main, George, Hess and Caroline, has been a parking lot for a very long time. Change is coming at last. - Google Maps 
In the late '80s, before condos came to town, a developer decided he'd be the first. He demolished some walk-up apartments, erected a pink, purple and green sales pavilion and started selling The Riviera — "Hamilton's Premiere Address."
The plan went bust. And ever since, that key piece of real estate — nearly two acres, bounded by Main, Hess, Caroline and George — has been nothing but parked cars.
Well, the tide has turned for condos and much else in downtown Hamilton. That long-lost piece of land has now sold for just over $20 million. In 1995, it was worth $450,000.
The purchaser is Bentall Kennedy, a $50-billion-or-so real estate investment company owned by Sun Life Financial. They're not ready to say much yet, but a query did bring an emailed statement from Brad Caco, BK's senior vice-president of development:
"There is an excitement in the downtown Hamilton core that gives us a great deal of optimism," he says. 
Factors in the purchase decision include "the emergence of the local technology and life sciences industries and the development of the LRT infrastructure."
The development, he says, "will be considerate of the present and future needs of the community." 
No specifics provided beyond that, but several sources say the goal is two or three residential towers on the site, a project that could be more than $300 million.
Toronto's Otis Group has owned that property for decades. Brian Otis says they've tried to make things happen on the site, including the McMaster downtown health centre that ended up a block east on Main.
Otis is a commercial developer, with projects across the province. So when it looked as though residential was the way things were heading for that downtown land, Otis says, it was time to take the offer. "But I have to tell you, I'm a little disappointed I wasn't the guy at the finish line."
Downtown Hamilton has changed, he says. "It's really coming along now … But it's still a pretty closed market, not the easiest for outsiders." 
One exception, he says, is developer Darko Vranich, who has erected several towers right next door in recent years. Vranich had wanted to buy the Otis land in the past, but the timing wasn't right. 
"Darko has a lot of energy," Otis says. "I should ask him for a blood transfusion."
Half-a-dozen blocks due east on Main, there's a new development where the property didn't sit empty for a minute.
It's another Vranich project — a 25-storey residential tower at Main and Walnut. He bought the property in the fall of 2017. The lawyers there moved out about six months later, demolition was underway by July, and foundation work began in a flash.
Soon a tower crane will arrive on site from a yard in Binbrook. Turns out Vranich recently bought two of these cranes, $750,000 US each, in New York state.
The other crane, now stretched out on Vranich land at King and Queen, will rise soon for a 30-storey student residence and a 10- to 12-storey Hampton Inn at that corner.
Over at Main and Walnut, new development is welcome. That piece of street needs it. 
But please, a quick salute to the building at that corner which fell so fast. Its moment of glory came early in 1964, when mayor Vic Copps officially opened the national headquarters of the Society of Industrial and Cost Accountants of Canada.
The building had been the district offices of Imperial Oil — along with a service station — and later became the Parker's dry cleaning plant.
But the accountants spent substantial money to change all that. As Spec writer Milford L. Smith reported 55 years ago:
"The asphalt pavement, oil-stained by tens of thousands of automobiles in the gas station days, has been torn up. In its place is a raised area in which grass and trees and flowers will be planted, restoring in part the Main Street East scene when palatial residences were set back from the roadway."
Old mansions on that stretch of Main? Hard to imagine. Everything changes, but it's good to know what came before.
PaulWilson.Hamilton@gmail.com

Tuesday, 16 April 2019

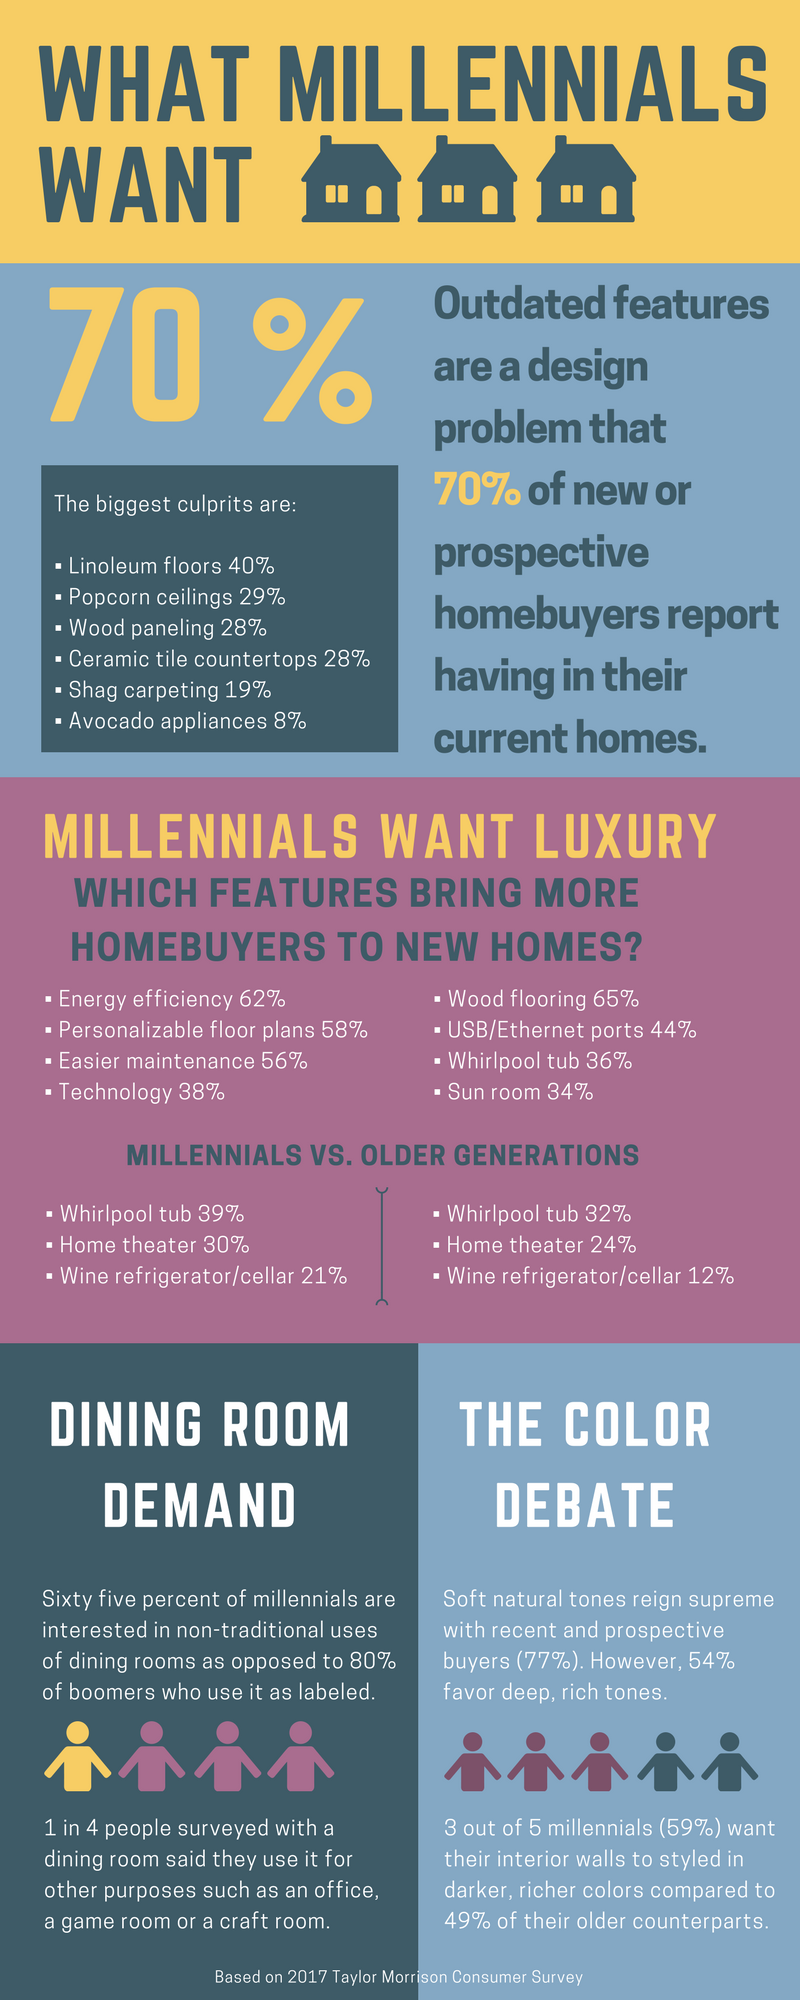
What design elements are millennials looking for in a home?


What design elements are millennials looking for in a home?

National consumer survey breaks down interior design preferences by generation

Advertisement
With millennials becoming the largest segment of homebuyers, it’s critical for homesellers and their real estate agents to know their design preferences. Thanks to the 2017 Taylor Morris Consumer Survey, we know what recent and prospective millennial homebuyers are into.

The 2017 Taylor Morris Survey, conducted by Wakefield Research, surveyed 1,000 American adults who have purchased a home in the past three years or who are likely to purchase a new home in the next three years.

Sunday, 14 April 2019

Five Ways To Tell If You're Cut Out To Be A Landlord

Five Ways To Tell If You're Cut Out To Be A Landlord


Investing in real estate by purchasing rental properties can be a smart way to balance your portfolio, hedge against inflation and build long-term wealth. Not everyone is cut out to be a landlord, though — but even if you feel you’re not landlord material, you can get the same portfolio benefits by investing in real estate indirectly through a private loan fund or a real estate investment trust. Here are five questions to help determine if investing directly in real estate is right for you.
1. Do you have 20% down payment and 5% to cover repairs and unexpected expenses?
Buying a rental property takes a much bigger down payment than buying a personal residence. Most lenders want at least 20% down, even if the property will generate enough income to pay the mortgage plus expenses like property taxes and hazard insurance. Having another 5% set aside to cover repairs and big-ticket expenses, such as replacing a roof or an HVAC system, may keep you from having to dip into personal funds to pay for unexpected problems.
2. How will you handle renters who don’t pay and the possibility of evicting tenants?
At some point, almost every landlord has to deal with tenants who stop paying rent. Eviction is a financial decision with emotional underpinnings. When tenants don’t pay rent, you still have to pay the mortgage, the property taxes, the water bill and all the other holding costs. But sometimes, nonpaying tenants are families with children or have unexpected circumstances like a serious illness or accident occur, leaving them unable to pay rent. If it’s too emotionally taxing to handle the eviction yourself, you can hire an attorney to represent you in court and movers to remove the tenants’ possessions from the property. Before becoming a landlord, you should know that the possibility of evicting a tenant might become a reality.
3. How do you feel about other people using your stuff?
Landlords hold security deposits because damage happens. Carpets get stained, hardwood floors get scratched and there is a fair amount of general wear and tear that should be expected in and on your property. As long as the cost to repair damages doesn’t exceed the security deposit, there shouldn’t be an issue. The real question becomes, what happens when the cost of repairs required exceed the security deposit? How will you confront your tenant to address these issues?  If contemplating this (somewhat common) scenario is stressful, becoming a landlord may not be an optimal option for you.
4. Can you wait at least 15 years for your investment to pay off?
Real estate is a long-term investment for a couple of reasons. First, the transaction costs are high. Real estate sales commissions, state and local transfer taxes, appraisals and settlement costs all reduce your resale profit. Second, the length of your mortgage dictates the monthly payment. The longer your keep your mortgage, the lower the monthly payment.
When buying a property, landlords typically choose a mortgage payment that can be covered by the monthly rent, plus expenses. When rents are relatively high compared to home prices, you might squeak by with a 15-year mortgage. In a market where rents and home prices are balanced, the monthly payment that best matches the rent price is typically tied to a 30-year mortgage. Both factors make investing in rental properties a long-term play.
5. What’s your risk tolerance?
All investments carry some level of risk, meaning how likely you are to lose your entire investment or even owe more than you invested. Real estate falls in the midpoint of the risk range. It’s less risky than commodities futures but more risky than investing in Treasury bills.
There are property owners whose home values still haven’t recovered from the real estate crisis a decade ago. And when property values fall, rents can fall, too. When rents fall, you can find yourself having to pay out of pocket to cover the monthly mortgage and expenses on your rental property. If the thought of declining property values will cause you to lose sleep, owning real estate as an investment may not be for you.
Purchasing a rental property with a mortgage timed to pay off before you retire can create a steady retirement income stream that rises with inflation. However, direct investment in real estate investment is unlike the other investments in your portfolio because it’s not a buy-it-and-forget-it proposition. It requires hands-on management of tenants, repairs and ongoing expenses. If becoming a landlord doesn’t seem like the best fit for you but you still wish to incorporate real estate in your investment portfolio, private loan funds and real estate investment trusts may be alternatives to investigate. With either option, investing in real estate can balance your portfolio and help you build wealth.

Monday, 8 April 2019

6 ways to pay off your mortgage faster

6 ways to pay off your mortgage faster

Stop focusing on the rate and pay attention to prepayment options 

by 
paying off your mortgage faster
While the Bank of Canada has yet to raise their overnight rate—a rate that dictates what happens with variable mortgage interest rates—there are changeswithin the current Canadian mortgage climate.
In late 2016, TD Canada raised it’s variable rate mortgage—not just for new mortgage business, but also for existing mortgage holders. The rate increase was in response to three factors: the new mortgage rule changes introduced by the federal government in early October 2016, which add extra costs to lendersand these costs are then passed down to borrowers; the increasing probability that fixed mortgage rates will soon rise, following an increase in U.S. treasury bond yields; and TD Bank’s current exposure to the residential mortgage market.
It’s still important to negotiate the best rate possible (read more on how to do that, here), but now, more than ever, it’s vital that we consider how to crush the mortgage debt.
Here are six simple strategies for paying off your mortgage faster:

1. Add an extra sum each month

Each month add a set amount to your regular mortgage payment. Even an extra $15 or $25 per payment adds up. For instance, if you paid bi-weekly and added an extra $25 per payment, after five years you would have reduced the principal loan by 2.5% over the life of the debt (assuming a 2.85% fixed five-year rate on a $450,000 mortgage amortized over 25 years), for more than $7,350 in savings.

2. Put your raise to work

Do you get a bonus from work? What about an annual raise? When your annual, monthly or hourly payroll increases, consider applying the extra to your mortgage. You won’t miss the money as you’re already disciplined about living on the original sum you were earning—and the extra funds will go a long way to reducing the principal mortgage debt.

3. Make a safe bet

If you want to pay-off your mortgage debt faster, a good, safe bet is to double-down on your regular mortgage payments in any given year. By paying double the amount you typically owe, say four times per year, you can shave a thousand or more off what you owe and this translates into months or even years off the amortization.

4. Use your tax refund

Getting a refund this year? Use your refund to pay down your mortgage. Your regularly scheduled payments won’t change, but when it comes time to renew you’ll be thankful for the lump-sum prepayment.

5. Retire your fixed income

If you invest in bonds or GICs, consider using these investments to pay off your mortgage principal once they mature. You’ll be trading in one low-risk investment—for another low-risk investment (a return on bonds or GICs for a paid off mortgage), so you won’t be adding risk to your expected, future return.

6. Use a windfall

If you recently came into some unexpected money—say, through an inheritance or because you won the lottery, or even an unexpected investment gain—use the sum to pay down your mortgage principal. Keep in mind that every lender and every mortgage have their own prepayment rules. Some allow monthly double-up payments, some allow as much as a 20% lump-sum prepayment (of your original mortgage principal). To save yourself from incurring a prepayment penalty read your mortgage document or contact your mortgage lender.

Saturday, 30 March 2019

Support for First-Time Home Buyers

Improving Affordability Today: Support for First-Time Home Buyers

To help make homeownership more affordable for first-time home buyers, Budget 2019 introduces the First-Time Home Buyer Incentive.
  • The Incentive would allow eligible first-time home buyers who have the minimum down payment for an insured mortgage to apply to finance a portion of their home purchase through a shared equity mortgage with Canada Mortgage and Housing Corporation (CMHC).
  • It is expected that approximately 100,000 first-time home buyers would be able to benefit from the Incentive over the next three years.
  • Since no ongoing payments would be required with the Incentive, Canadian families would have lower monthly mortgage payments. For example, if a borrower purchases a new $400,000 home with a 5 per cent down payment and a 10 per cent CMHC shared equity mortgage ($40,000), the borrower’s total mortgage size would be reduced from $380,000 to $340,000, reducing the borrower’s monthly mortgage costs by as much as $228 per month. Terms and conditions for the First-Time Home Buyer Incentive would be released by CMHC.
  • CMHC would offer qualified first-time home buyers a 10 per cent shared equity mortgage for a newly constructed home or a 5 per cent shared equity mortgage for an existing home. This larger shared equity mortgage for newly constructed homes could help encourage the home construction needed to address some of the housing supply shortages in Canada, particularly in our largest cities.
  • The First-Time Home Buyer Incentive would include eligibility criteria to ensure that the program helps those with legitimate needs while ensuring that participants are able to afford the homes they purchase. The Incentive would be available to first-time home buyers with household incomes under $120,000 per year. At the same time, participants’ insured mortgage and the Incentive amount cannot be greater than four times the participants’ annual household incomes.
Budget 2019 also proposes to increase the Home Buyers’ Plan withdrawal limit from $25,000 to $35,000, providing first-time home buyers with greater access to their Registered Retirement Savings Plan savings to buy a home.

Friday, 29 March 2019

Sliding/Stackable Glass Doors Erase the Boundary Between Inside and Outdoors

 By Terri Williams  

Abundant light

Perfect view


Home Aesthetic

Homebuyers
Practical