Tuesday, 26 March 2019

Paying off your mortgage faster

Paying off your mortgage faster

To pay off your mortgage faster, consider putting extra money toward your mortgage.
Your mortgage contract may allow you to:
  • increase the amount of your regular payments
  • make a lump-sum payment
Your lender calls this a prepayment or prepayment privilege.

Increase your payments

Increasing the amount of your regular payments, even by a small amount, may help you pay off your mortgage faster.
You may only be able to increase your payments by a certain amount each year. The amount will be written in your mortgage contract. If you increase your payments by more than your prepayment privileges allow, you may have to pay a prepayment penalty.
Normally, once you decide to increase your payments, you won’t be allowed to lower them until the end of the term. The term is the period of time that your mortgage agreement is in effect, including your interest rate and terms and conditions.
Check your mortgage contract or contact your mortgage lender to find out about your prepayment options.

Example: increasing your payments

Suppose you’re considering a mortgage of $350,000 that you’ll pay back over 25 years.
You want to decide if paying $100 more a month will help you save money.
Assume the following:
  • your mortgage lender tells you that you must pay at least $1,841 a month
  • your interest rate of 4% remains the same throughout your 25-year mortgage


If you pay an extra $100 a month during the life of the mortgage, you'd:
  • save more than $19,000
  • pay off your mortgage more than 2 years earlier

Make a lump-sum payment

You can make a lump-sum payment on top of your regular mortgage payments to reduce the outstanding balance of your mortgage.
You may only be able to put a limited amount of money toward your mortgage. The amount will be written in your mortgage contract. If you put more money toward your mortgage that your prepayment privileges allow, you may have to pay a prepayment penalty.
Lump-sum payments can be made:
  • before the end of your mortgage term
  • at the end of your term
  • at certain times during your mortgage contract
  • on certain dates set out in your mortgage contract
Check your mortgage contract or ask your mortgage lender to find out about your prepayment options.

Example: making a lump-sum payment

Suppose you’ve got a mortgage of $350,000 that you’ll pay back over 25 years.
Throughout the year, you were able to save an extra $10,000 to put toward your mortgage. You decide to put the money toward your mortgage at the start of your term’s second year.
Your mortgage contract allows you to make one lump-sum payment per year that is no more than 10% of what you owe on your mortgage.
This means you can make a prepayment up to $35,000 ($350,000 x 10%).
Assume that the interest rate of 4% would remain the same for the rest of the mortgage.


Making a $10,000 prepayment toward your mortgage would:
  • allow you to pay off your mortgage more than 1 year earlier
  • reduce how much interest you'll pay by more than $15,000

Prepayment penalties

If you put more money toward your mortgage than the maximum amount allows, you may have to pay a prepayment penalty.
Read your mortgage contract carefully. Make sure you understand the details about penalties.

Keep your monthly payments the same when you renew your mortgage

When you renew or renegotiate your mortgage, you may be able to get a lower interest rate. If so, you’ll have the option to reduce the amount of your regular payments. If you decide to keep your regular payments the same, you'll be able to pay off your mortgage faster.

Example: keeping the payments the same when you renew your mortgage

Suppose you’ve got a mortgage of $350,000 that you’ll pay back over 25 years. At a 5% interest rate, your payments are $2,036 each month. When you renew your mortgage after a 5-year term, your interest rate has gone down from 5% to 4%.
For the remaining 20 years of your mortgage, you want to decide if you should pay the new minimum monthly payment of $1,872 or continue to pay $2,036 each month.
Assume the following:
  • the amount you owe on your mortgage is $309,776
  • you renew your mortgage for another 5-year term
  • your new minimum monthly payment is $1,872 each month
  • your new interest rate of 4% would remain the same for the rest of the mortgage


By keeping your monthly payments the same at the lower interest rate for the rest of your mortgage, you'd:
  • save almost $18,000
  • pay off your mortgage more than 2 years earlier
You may also consider making accelerated weekly or accelerated biweekly payments.

Choose an “accelerated” option for your mortgage payments

An accelerated payment option lets you make weekly or biweekly payments while putting about the same amount of money toward your mortgage as a monthly payment.
Accelerated payments can save you money on interest charges. By accelerating your payments, you make the equivalent of one extra monthly payment per year. You’ll likely not notice a big difference in the amount of your payments, yet it may save you a lot of money in interest.
Check your mortgage contract or contact your mortgage lender to know more about your payment options.

Related links

Sunday, 17 March 2019

Investing 101: 10 Essential Tips For New Real Estate Investors


Investing 101: 10 Essential Tips For New Real Estate Investors


POST WRITTEN BY
Daniel Berman


GettyGETTY
Starting out in a challenging behemoth of an industry like real estate may seem daunting at first. With so many factors and risks involved, the simple act of contemplating where to begin can be overwhelming. After all, it’s one of the largest and most regulated sectors of the U.S. economy, accounting for approximately $30 trillion. As with most things in life, however, once you get over the initial hurdle of getting started, opportunities begin to present themselves and everything becomes clearer with time.
What I've learned over my career may help you in your real estate investment journey and hopefully provide the impetus new investors need to take the first exciting step.
1. Find your vehicle. 
It’s all about making that initial, defining decision on what you want to invest in. In order to find the vehicle, you need to do your fair share of research. Find out what problem currently exists in the market or what service is lacking
In my case, after two or three years of working in retail, I realized that the only person making money in the equation was the landlord. Additionally, I felt that the rental market was very strong and realized that this is a service people are always going to need — whether it be commercial, offices, apartments, etc. It was at that point after identifying a basic need that I began to look into real estate investing. This was going to be my vehicle.
2. Educate yourself. 
It sounds like a cliché, but educating yourself is crucial. You need to learn absolutely everything you can about the investment vehicle you choose. You have to become an expert — no ifs, ands or buts about it.
I began to take classes, attend seminars and workshops and read any book I could get my hands on. People want to make sure you know what you’re talking about.
3. Hone in on the product. 
Once you finally decide what to invest in, the next step is to determine the specifics. After taking a few real estate classes, I decided to begin with basic residential investment. Over the years, people have often asked me why I chose residential over commercial. The simple answer is that residential investments are smaller, and I wanted to start out small and gradually move upward.
4. Make a good name for yourself. 
Your reputation, identity and credibility rest on your financial standing and experience. By financial standing, I’m talking about your financial history, i.e., bankruptcy, credit score, etc. Some may be discouraged by past financial problems and automatically deem themselves unqualified to enter the business. However, most people can work hard to clean their slates and move forward.
Moreover, your track record and experience matter. They will be used to measure you against others in your field, and they define who you are and what you’ve accomplished. Create a story for yourself that you’ll be proud to share.
5. It’s all about the deal. 
If you don’t have much experience or an extensive track record but you do have a good deal at hand, investors will come regardless. A good deal is one that makes sense, is the right price and has the potential to provide a good return on investment. So, if you’re armed with just the right tools and knowledge, you’re an honest person and, most importantly, your deal makes sense, then investors will flock to you.
6. Don't forget about location, location, location. 
This phrase has become so overused that we tend to ignore it. Love it or hate it, location and the demographics of certain locations are paramount when it comes to investing in real estate.
When I started out, the first properties I bought were single-family houses in Sunrise, Florida. It was a middle-class location with fairly mid-level prices and the ratio of rent to price point was good. I later went on to purchase duplex and triplex properties, then multifamily and finally hotels. It’s a long and intricate process, but the key is to start small and work your way up little by little.
7. Create a powerful presentation that will speak for itself. 
People like visuals. You need to create a rousing and informative presentation that captures the essence of your company in a way that’s both efficient and aesthetically pleasing. It should include who you are, what you’ve done and what you offer. This step is integral to the process as it consolidates everything I‘ve mentioned so far and can be a make-or-break moment when it comes to potential investors.
8. Prioritize funding. 
This step is pretty self-explanatory: For your business to succeed, you need investors. In the beginning, most of your investors will likely be friends and family who are gracious enough to lend a hand. After a while, you might get some friends of friends to invest through word of mouth or simple marketing, and slowly but surely, you’ll begin to build your network of investors.
9. Honor your commitments. 
This needs to remain true no matter what. Your integrity as a person is invaluable. This business involves risk and requires a great deal of trust between all parties. Your word is the most valuable thing you have to offer.
10. Build a strong team. 
You need to surround yourself with honest, intelligent and highly motivated individuals. Among these should be an attorney, an accountant, several realtors and marketing pros.

Saturday, 9 March 2019

What Size Storage Unit Do I Need? And Other Questions to Ask When Picking a Facility


What Size Storage Unit Do I Need? And Other Questions to Ask When Picking a Facility

 | Oct 29, 2018
If you need a storage unit, there are many questions you should ask before you pick one. For example: What size unit do you need? How much does a storage unit cost?
Choosing a storage unit may seem daunting at first, but if you've reached that point where you've run out of space in your home for all of your belongings, it's time to dive in. Here are some questions to ask to ensure you find the right storage unit for you.

What size storage unit do I need?

Before you begin your search for the right unit, make a list of all the items you'll be storing. This way you can save time by focusing only on storage facilities that meet your needs in terms of size.
Storage units generally range in size from 5-by-5 to 10-by-25 feet, and some may be even larger. Wondering which size is best for you? Picture these:
  • A 5-by-5 unit is the size of a small closet and could hold several small- to medium-size boxes, a dresser, or a single bed.
  • A 5-by-10 unit is comparable to a walk-in closet, which could hold larger furnishings such as a queen-size bed or couch.
  • A 10-by-10 unit could hold two bedrooms' worth of furnishings.
  • A 10-by-20 unit is equal to a standard one-car garage, and could hold the contents of a multiple-bedroom house.
Prefer not to climb over mountains of tubs and boxes to track down something stashed at the far reaches of that space? Choose a unit that allows entry on either side.
"How many times do you put something in the back of a closet only to find that you need it? The same thing happens with a storage unit," explains Willie Dvorak, owner of AAA Storage in Mellette, SD. "Ensuring you can access your goodies from both sides of the unit makes it that much easier to find what you need quickly and safely."

How much does a storage unit cost?

Unless you're filthy rich (and then you probably have a big house with ample storage), you'll want to know how much this unit will set you back each month. CostHelper.com breaks down how much you can expect to pay on average:
  • A 5-by-5 unit costs about $40 to $50 a month.
  • A 10-by-20 unit costs about $95 to $155 a month.
  • A 20-by-20 unit costs about $225 a month.


Is this storage unit easily accessible?

What good is having a storage unit if it's hard to access, both in terms of its location and its design? Dvorak outlines what to look for when selecting a facility.
"If you can't get your vehicle close enough to the unit, you'll be lugging your stuff feet—even yards—in both directions," he says. "While it may not seem like a long walk as you look at the unit, imagine carrying all of your stuff back and forth all of that way. When you're storing stuff, every step is a nuisance. And, when you are stressed, you're more prone to accidents. Turning that rental truck around just adds to the stress. Be sure you can pull up the unit and get your vehicle turned around without any trouble."

What are the storage facility's hours?

Once you've unloaded your belongings, you still want to know that you can reach them in a hurry should you have the desire.
"It's hard to predict when you'll need that hiking gear you haven't used for years, Grandma's scrapbook, or that special award you want to show off," Dvorak notes. "Don't miss out because you think of it after they've locked things up for the night (or weekend). Make sure you can access your stuff 24 hours a day, 7 days a week."

What's the payment policy?

Fred Levine, founder of Little Hard Hats, recommends reading all of the fine print of the contract to determine how long the price is guaranteed.
"They routinely get you in, then shortly thereafter, once you’ve moved all your stuff in, they sometimes raise the rates," he cautions.
"Understanding the payment policy can also help you make decisions about a storage facility," says Caitlin Hoff of consumersafety.org. "What is the late fee or policy? Some facilities will auction your storage unit if rent is not paid after a certain amount of time. Does your facility allow for online payments? If it doesn't, do you have to pay in person? Knowing the full extent of the policy can narrow down a list of facilities."

What type of security is used?

Ask how the storage unit facility is secured. Is there a guard? Video surveillance? Alarms? Is the area well-lit? Also, don't assume the facility is going to cover damages to your possessions inside the storage unit in case of an accident. Check your homeowners policy, and purchase a rider if necessary.

Is it climate-controlled?

Depending on the items you are looking to store, you might debate whether or not you want a climate-controlled storage unit. A climate-controlled unit is better for items such as appliances or antiques that might be damaged in extreme temperatures.

How are pests handled?

No one wants to find that a family of critters has turned your family heirlooms into their home.
"If you are looking at an outdoor storage unit, you want to ask about pest control," says Hoff. "Ask if they have had issues with any insects or critters, and find out how they handle these situations."
Eric Hoffer, president of Hoffer Pest Solutions, suggests doing your own detective work when you preview the facility.
"Overgrown bushes, unkempt landscaping brushing up against the side of the building, and overflowing trash cans are not only a sign that maintenance may not be a priority for a storage facility, but these can be things that attract pests like rodents and roaches close to the building," he says. "All it takes is a small crack or gap in the wall to allow pests inside."
If you're going to the trouble of storing your items for later use, you want to know they'll be in the best shape possible when you want them. Finding the right facility can make all the difference.

Wednesday, 6 March 2019

Bank of Canada leaves key interest rate unchanged at 1.75%

Bank of Canada leaves key interest rate unchanged at 1.75%


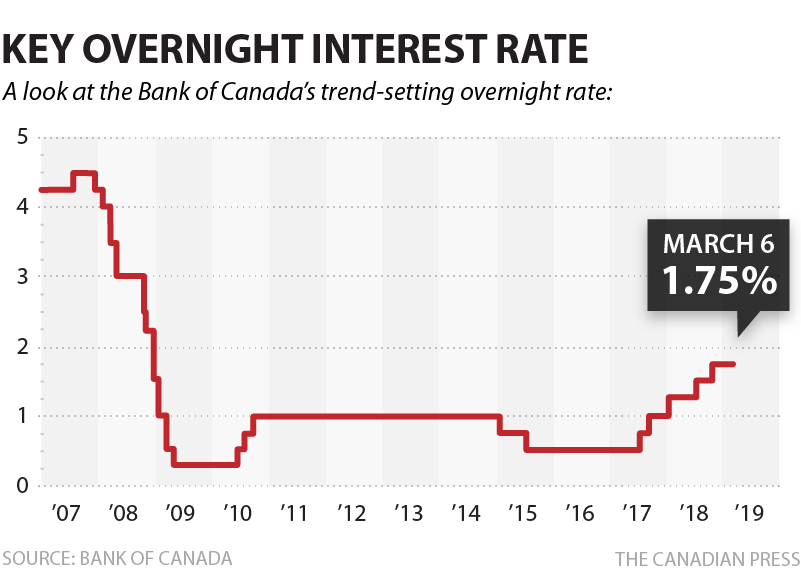
As widely expected by economists and investors, the Bank of Canada left its trend-setting interest rate unchanged at 1.75 per cent on Wed., March 6, 2019.
Sean Kilpatrick/CP
 A A 
The Bank of Canada (BoC) is keeping its key interest rate target on hold at 1.75 per cent on Wednesday, citing concerns about the global economy and Canada’s own recent performance.
The central bank said the current slowdown in the world economy has been “more pronounced” than it anticipated in its January forecast. Trade uncertainty is “weighing heavily” on economic performance around the globe, even as progress in the U.S.-China trade talks had helped to improve market sentiment, the BoC said in a statement.
In Canada, the BoC also expects the economy to be weaker in the first half of 2019 than it projected in January, adding it is watching developments in household spending, oil markets and global trade.
The Bank of Canada has raised its rates five times since July 2017, though it has held its overnight interest rate steady at 1.75 percent since October of last year.
BANK OF CANADA KEY OVERNIGHT RATE
It made clear on Wednesday that future hikes were still on the table, but not imminent.
“Governing Council judges that the outlook continues to warrant a policy interest rate that is below its neutral range,” it said in a statement, adding that there was “increased uncertainty about the timing of future rate increases.”
The Bank of Canada said it expects inflation to be slightly below its 2 percent target for most of 2019 on temporary factors, including lower energy prices and a wider output gap.
WATCH: Interest rates expected to move higher ‘over time,’ says Bank of Canada governor Stephen Poloz
Recent data showed consumer spending and the housing market were soft, it said, despite strong growth in employment and labor income, with exports and business investment falling short of expectations.
Given the mixed picture, the central bank said it would “take time to gauge the persistence of below-potential growth and the implications for the inflation outlook.”
Last month, Bank Governor Stephen Poloz said interest rates still need to move up into the neutral range, pegged at between 2.5 percent and 3.5 percent, but he warned that the path back was “highly uncertain.”
Indeed, the central bank’s neutral rate range has become contentious, with bond investors warning that it may be too high for Canada’s debt-laden economy, hurting its use as a signpost for monetary policy.
— With files from the Canadian Press and Global News reporter Erica Alini

Sunday, 3 March 2019

5 Renavation secrets that pay off

5 Renovation Secrets That Pay Off

Spoiler: Size matters―when it comes to your kitchen island, that is.

family home, home value, transitional home
SARAH ELLIOT PHOTOGRAPHY
Designer Julie Kantrowitz knows what makes a home sellable. For a recent spec house (short for "speculation," that is, homes builders create without a buyer yet on board) she designerd with builder Bob Gallo of Chestnut Hill Development, the New Jersey-based founder of JK Interior Living looked to the projects she's designed for clients and her knowledge of the home market to create a family home that is at once elegant and livable. For the historic property in Ridgewood, New Jersey, Kantrowitz "basically went down to the studs," the designer recalls, retrofitting a 1932 building to create a contemporary home that maintains the charm of its original era. In the process, she demonstrated some of her best learnings about creating a comfortable home that's also ripe for eventual resale.

Make Room for Family

family home, home value, transitional home
The kitchen of a Ridgewood, New Jersey, home by JK Interior Living. The pendants are from Visual Comfort.
SARAH ELLIOT PHOTOGRAPHY
ADVERTISEMENT - CONTINUE READING BELOW
We've all heard it before: The kitchen is the new family room. Between open-plan spaces that merge the eating and living spaces and the ubiquitous kitchen island that begs pulling up a chair, the kitchen has never been more the heart of the home. And as such, it has to be able to accommodate any and everyone. "A bigger kitchen is in demand for sure," Kantrowitz says. "With a large island—trying to accommodate as many seats around the island as possible is a big thing." This is especially true for larger family homes, where buyers expect that all residents—and a bevy of friends—can sit together. "If you’re looking at 5-6 bedroom homes, logically, they're for families of, on average, 5," Kantrowitz says. "So you want to make sure that the kitchen can accommodate these larger families."

Don't Forget Utility 

image
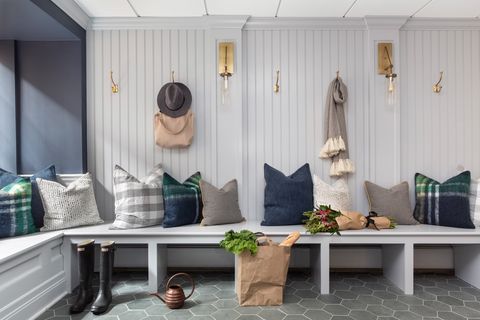
The mudroom provides plenty of storage.
SARAH ELLIOT PHOTOGRAPHY
Another thing bigger families need? A place to throw keys, backpacks, and all other manner of ephemera that a growing brood attracts. In this home, Kantrowitz carved out a mudroom from a previously unused basement space—though she's had clients go to even further extremes for this kind of space: "People are adding on additions literally for the sake of having a mudroom," says the designer. "Everybody is looking for mudrooms now, whether in new homes or older ones. That’s another example of what I did to kind of modernize the home to make it more attractive to younger, larger families." 
Since this space is primarily a functional one, Kantrowitz ensured lots of storage, and added a table as a catchall for keys or mail. She covered the floors in slate for their durability, a decision echoed in the bathroom, where the designer nixed marble in favor of quartz, which better withstands daily wear—for no aesthetic sacrifice. "Quartz now is manufactured so well that it’s becoming a legitimate alternative," she says. "It’s not grainy up close; it has beautiful characteristics."

Get Creative with Usage 

image
The home’s wine pantry.
SARAH ELLIOT PHOTOGRAPHY
ADVERTISEMENT - CONTINUE READING BELOW
If a space isn't used: Think of what would make you use it more. In this case, Kantrowitz turned an overlooked side space off the kitchen into a butler's pantry and a statement wine room. "We're asking ourselves, 'what are the features in a forever home that we’d be interested in?'" explains Kantrowitz of her decision to spring for these types of spaces. But make no mistake: Just because these rooms become functional for storage doesn't mean they can't be beautiful. The designer created custom cabinetry with chicken wire fronts—to add a sense of depth in a shallow space—in the wine room, and then accessorized with statement sconces from Hudson Valley Lighting. 
image
The butler’s pantry.
SARAH ELLIOT PHOTOGRAPHY123

Meanwhile, in the butler's pantry, glass-front cabinets make for storage that doubles as "an intentional accent," explains Kantrowitz. 

Preserve the Best of History

"At every opportunity I kept the original," stresses the designer of the home's historic attributes. That meant maintaining the kitchen's parquet floors and the jaw-dropping leaded-glass windows in the master bath. "I personally love older homes," she explains. "I love to incorporate the charming details that were original to any home. A lot of these details, if you do it mindfully, you can update in a clean and sophisticated way without compromising on the original design."
One surprising example? A certain dated wood in the mudroom that Kantrowitz found to be a surprisingly pleasing pair with the new design after a simple refinish. "In the '90s there was this very specific wood color, this kind of shiny oak, and people cringe when they see it," the designer laughs. "But when we sanded it down and put a clear coat of poly on it, we found it works really great with grays and blues in that room."
family home, home value, transitional home
The home’s stunning bath features original windows and a contemporary update on herringbone floors.
SARAH ELLIOT PHOTOGRAPHY
ADVERTISEMENT - CONTINUE READING BELOW
When the original does feel too dated, consider updates that still tie back to the classics, like Kantrowitz did in the master bath. "Some things are just timeless, like herringbone laid tile, so I’ll do wider plank herringbone to make it feel cleaner but still have that classic look," says the designer. 

Use Your Space Wisely

While it might be tempting to chop larger closets and baths up to make multiples, Kantrowitz cautions homeowners to think twice. "For this home, the master bath and the master closet used to be a his-and-hers," she says. "The builder wanted to keep that layout and just update it, and I said I’d prefer to have one really large bath and one really large closet. While the his-and-hers is popular, you are still compromising square footage. It’s not necessarily something I recommend."
The larger master bath affords space for a freestanding tub, which emphasizes the original windows and lends the space a grand, luxurious feel—much better than two cramped baths. 

Ensure Good Flow

Any designer worth her trade discount will tell you that a good flow is the key to any well-loved space. Here, Kantrowitz ensured that both with floor plan and visual cues. "The family room is immediately adjacent to the large kitchen," optimizing traffic between the two most-used parts of the house. Meanwhile, in the powder room down the hall, the designer explains: "I wanted the space to feel connected to the rest of the house, so instead of beginning the tile at the door frame, I decided to tie in the hardwood floor as a border surrounding the tile." 

Don't Be Afraid of the Dark 
family home, home value, transitional home
In the laundry room, dark cabinets and a patterned floor add interest despite small square footage.
SARAH ELLIOT PHOTOGRAPHY

A dark navy on cabinets in the laundry room may come as a surprise, given that white and cream cabinets have become a go-to. But Kantrowitz is a fan of a little darkness. "I've been using black and really dark navy a lot lately, and I love it," she says. "In just the right dose I think it’s so sophisticated and chic—if you do it in small doses it’s not overpowering." 

It's O.K. to Make a Statement (or Two)

Another eye-catcher in the laundry room? The patterned floor, courtesy of some high-impact cement tiles. "Everyone wants to do something fun and creative, but nobody wants to take those types of risks in a foyer or a main space, so the best applications for those types of creative and unique materials are in rooms like a laundry room or a mudroom, or a child’s bath," explains the designer. "It’s something that’s not in viewable sight but that you’re in often enough to enjoy." No further argument needed.